LTCG & STCG – Latest Tax Rules Every Investor Must Know (2026 Guide)
Introduction Investing in shares, mutual funds, exchange-traded funds (ETFs), and other financial assets has become increasingly popular in India. While earning good returns is every investor’s goal, understanding the tax implications of these investments is equally important. One of the most confusing topics for investors is the difference between Long-Term Capital Gain (LTCG) and Short-Term Capital Gain (STCG). Many people know they have to pay tax on profits from investments, but they are often unsure about how those profits are classified, how they should be reported in the Income Tax Return (ITR), and what records they should maintain. Incorrect reporting of capital gains can result in errors in your Income Tax Return, delayed refunds, or notices from the Income Tax Department. With the Income Tax Department using advanced digital reporting systems like AIS (Annual Information Statement), TIS (Taxpayer Information Summary), and Form 26AS, it has become more important than ever to disclose investment income accurately. Whether you’re a first-time investor or an experienced trader, understanding LTCG and STCG will help you make informed investment decisions and remain tax compliant. If you’re searching for the Top CA in Jaipur, Best CA in Jaipur, expert Income Tax Consultants, or professional assistance for ITR Filing in Jaipur, this guide will help you understand the basics before filing your return. What are Capital Gains? A capital gain is the profit earned when you sell a capital asset for more than its purchase price. Capital assets may include: Listed Shares Mutual Funds Exchange Traded Funds (ETFs) Bonds Property Gold Other eligible investments If you sell an asset at a loss, it is generally referred to as a capital loss. Start Your Company In Just A Click —-! Click Here !—- What is Short-Term Capital Gain (STCG)? A Short-Term Capital Gain arises when a capital asset is sold within the holding period prescribed under the Income Tax Act for that category of asset. The exact holding period depends on the nature of the investment. Short-term gains are taxed according to the applicable provisions of the Income Tax Act. What is Long-Term Capital Gain (LTCG)? A Long-Term Capital Gain arises when an asset is sold after completing the prescribed holding period under the Income Tax Act. Long-term investments generally receive different tax treatment from short-term investments, subject to the applicable law. Why Should Investors Understand LTCG & STCG? Understanding the difference helps you: File your ITR correctly. Avoid incorrect tax calculations. Plan investments efficiently. Maintain proper tax records. Reduce the chances of Income Tax notices. Make informed financial decisions. Real-Life Example 1 Rahul purchased shares of a listed company and sold them after a relatively short holding period. He assumed that all investment profits were taxed in the same manner. After consulting a tax professional, he learned that the tax treatment depends on the holding period and the type of investment. This helped him file his Income Tax Return correctly. Investments Covered Under Capital Gains Capital gains taxation may apply to: Equity Shares Mutual Funds ETFs Bonds Debentures Property Gold Investments Other capital assets Different assets may have different holding periods and tax rules. Documents Required Before Filing Your ITR Before preparing your return, keep the following documents ready: Broker’s Capital Gains Statement Contract Notes Demat Account Statement Mutual Fund Statement AIS TIS Form 26AS Bank Statements These records help ensure accurate reporting. Importance of AIS & TIS AIS and TIS provide information about many financial transactions reported to the Income Tax Department. Before filing your ITR: Compare your broker’s reports with AIS. Verify capital gains entries. Check TDS details in Form 26AS. Reconcile all investment transactions. This helps reduce errors and improves compliance. Real-Life Example 2 Priya invested in several mutual funds through SIPs. During the financial year, she redeemed units from different schemes. Initially, she planned to report only one transaction. After checking her AIS and capital gains statement, she identified all the transactions and filed an accurate return. Common Mistakes Investors Make Not Reporting Capital Gains Many taxpayers believe that only salary income needs to be reported. Capital gains should also be disclosed in the Income Tax Return. Ignoring AIS Ignoring AIS can result in mismatches between your return and the Income Tax Department’s records. Using Incorrect Purchase Cost Always rely on authentic investment records. Forgetting Dividend Income Dividend income should also be considered wherever applicable. Filing the Wrong ITR Form Selecting the correct ITR form is equally important. Tips for Accurate Capital Gains Reporting Maintain complete investment records. Download annual capital gains statements. Keep all contract notes safely. Verify transactions with AIS and TIS. Reconcile Form 26AS. File your ITR before the due date. Consult a Chartered Accountant whenever required. Real-Life Example 3 Amit regularly invested in shares and ETFs. At the end of the financial year, he had hundreds of transactions. Instead of calculating everything manually, he downloaded his broker’s capital gains report and consulted a tax professional. This saved time and helped him file an accurate ITR. Why Professional Tax Guidance Matters Capital gains taxation can become complicated when you have: Multiple investment accounts SIP investments Frequent share trading Dividend income Different categories of capital assets Large transaction volumes An experienced tax consultant can help you: Calculate capital gains accurately. Review broker statements. Verify AIS and TIS. Choose the correct ITR form. Report all transactions properly. Claim eligible tax benefits wherever applicable. Avoid Income Tax notices. This is why many taxpayers search online for: Top CA in Jaipur Best CA in Jaipur ITR Filing in Jaipur Income Tax Consultants ITR Filing Near Me Professional assistance ensures accurate compliance while reducing filing errors. Tax Planning Tips for Investors Good tax planning starts before selling your investments. Consider these practices: Keep records updated. Review your portfolio regularly. Track every purchase and sale. Preserve contract notes. Check AIS before filing. Maintain dividend records. Consult professionals before making major financial decisions. Conclusion Understanding the difference between LTCG and STCG is essential for every investor. Correct reporting of capital gains helps you remain compliant, avoid
ITR Filing for Freelancers, Consultants & Professionals: Complete Guide for Hassle-Free Tax Filing
Introduction The way people work has changed dramatically in recent years. Today, thousands of Indians are earning independently as freelancers, consultants, doctors, architects, lawyers, designers, software developers, digital marketers, YouTubers, influencers, content creators, photographers, and other professionals. While being self-employed offers flexibility and higher earning potential, it also comes with the responsibility of managing taxes. Unlike salaried employees, freelancers and professionals do not receive Form 16 from an employer, and in most cases, no one calculates their taxes for them. They must maintain income records, calculate taxable income, pay advance tax (where applicable), claim eligible deductions, and file their Income Tax Return (ITR) correctly. Many freelancers unknowingly make mistakes such as underreporting income, ignoring TDS credits, missing business expense deductions, or filing the wrong ITR form. These errors can lead to notices, penalties, delayed refunds, and unnecessary stress. This is why many self-employed individuals consult experienced Income Tax Consultants, the Top CA in Jaipur, or the Best CA in Jaipur for accurate ITR Filing in Jaipur and proper tax planning. In this guide, we’ll explain everything freelancers, consultants, and professionals need to know about ITR filing in simple, easy-to-understand language. Who is Considered a Freelancer or Professional? A freelancer or professional is someone who earns income independently instead of working as a full-time employee. Common examples include: Software Developers Graphic Designers Digital Marketers Chartered Accountants Lawyers Doctors Architects Interior Designers Business Consultants Financial Advisors Content Writers Photographers Videographers YouTubers Social Media Influencers Online Trainers Coaches Bloggers If you receive payments directly from clients, you’re generally responsible for your own tax compliance. Start Your Company In Just A Click —-! Click Here !—- Why is ITR Filing Important? Many freelancers believe that if tax has been deducted by clients, they don’t need to file an ITR. This is incorrect. Filing your Income Tax Return offers several benefits: Legal tax compliance Claim tax refunds Carry forward eligible business losses Easier loan approvals Better visa documentation Improved financial credibility Avoid Income Tax notices Even if your income is below the taxable limit in certain situations, filing an ITR can still be beneficial. Real-Life Example 1 Rahul is a freelance graphic designer who works with clients in India and abroad. Some clients deducted TDS before making payments. Initially, Rahul assumed the deducted TDS settled all his tax obligations, so he skipped filing his ITR. Later, he discovered he was eligible for a refund because excess TDS had been deducted. After filing his return with professional assistance, he successfully claimed his refund. Sources of Income for Freelancers Freelancers may earn income from multiple sources, including: Client Projects Professional Consultancy Online Platforms Foreign Clients Affiliate Marketing Blogging YouTube Digital Courses Commission Income Advertising Revenue Speaking Assignments Every source of income should be reported correctly while filing the ITR. Maintain Proper Books of Accounts One of the biggest mistakes freelancers make is not maintaining proper financial records. Keep records of: Client invoices Payment receipts Bank statements Business expenses GST records (if applicable) TDS certificates Investment details Good documentation makes tax filing much easier. Business Expenses You May Be Able to Claim Freelancers often incur genuine business expenses that may reduce taxable income. Examples include: Laptop and computer expenses Internet bills Mobile bills Office rent Electricity Software subscriptions Professional memberships Business travel Office supplies Marketing expenses Website maintenance Domain and hosting charges Accounting fees Only claim expenses that are genuine, properly documented, and allowable under the Income Tax Act. Real-Life Example 2 Priya is a freelance digital marketing consultant. Earlier, she paid tax on her entire income because she wasn’t aware that several business-related expenses could be considered while calculating taxable income. After consulting a tax professional, she maintained proper expense records and significantly optimized her tax liability through legitimate deductions. Choosing the Correct ITR Form Selecting the correct Income Tax Return form is extremely important. The appropriate form depends on factors such as: Nature of profession Total income Business income Presumptive taxation eligibility Other income sources Using the wrong ITR form may result in a defective return or delays in processing. Understand Presumptive Taxation Certain eligible professionals and businesses may benefit from the presumptive taxation scheme, which simplifies tax compliance by reducing bookkeeping requirements. However, eligibility depends on the nature of the profession and applicable provisions of the Income Tax Act. Consulting a tax expert can help determine whether this option is suitable for your situation. Advance Tax Responsibility Unlike salaried employees, freelancers generally do not have employers deducting tax every month. If your estimated tax liability exceeds the prescribed limit, you may need to pay Advance Tax during the financial year. Failure to do so may result in interest under the Income Tax Act. Planning your taxes throughout the year helps avoid surprises. Real-Life Example 3 Amit is an IT consultant earning from multiple corporate clients. He ignored advance tax payments because no one reminded him. At year-end, he not only had to pay the pending tax but also additional interest. Since then, he has been planning his taxes quarterly with professional guidance. Check TDS Before Filing Many clients deduct TDS before making payments. Before filing your ITR, verify: Form 26AS AIS TIS TDS certificates This ensures you receive proper tax credit. Report Foreign Income Correctly Many freelancers receive payments from overseas clients through platforms or direct bank transfers. If you earn foreign income: Maintain payment records Keep foreign remittance details Report income correctly wherever applicable Professional guidance is especially useful in such cases. Common Mistakes Freelancers Make Avoid these common errors: Not Reporting All Income Include income from every client. Mixing Personal & Business Expenses Maintain separate records. Ignoring TDS Credit Always reconcile with Form 26AS. Choosing the Wrong ITR Form Verify eligibility before filing. Not Paying Advance Tax May lead to additional interest. Poor Documentation Maintain invoices and receipts. Filing at the Last Minute Increases the risk of mistakes. Real-Life Example 4 Rohit is a freelance software developer who received payments from several clients throughout the year. He kept no invoices and relied
Can Indian Gamers Legally Receive Payments in USD? Tax & FEMA Rules Explained (Complete Guide 2026)
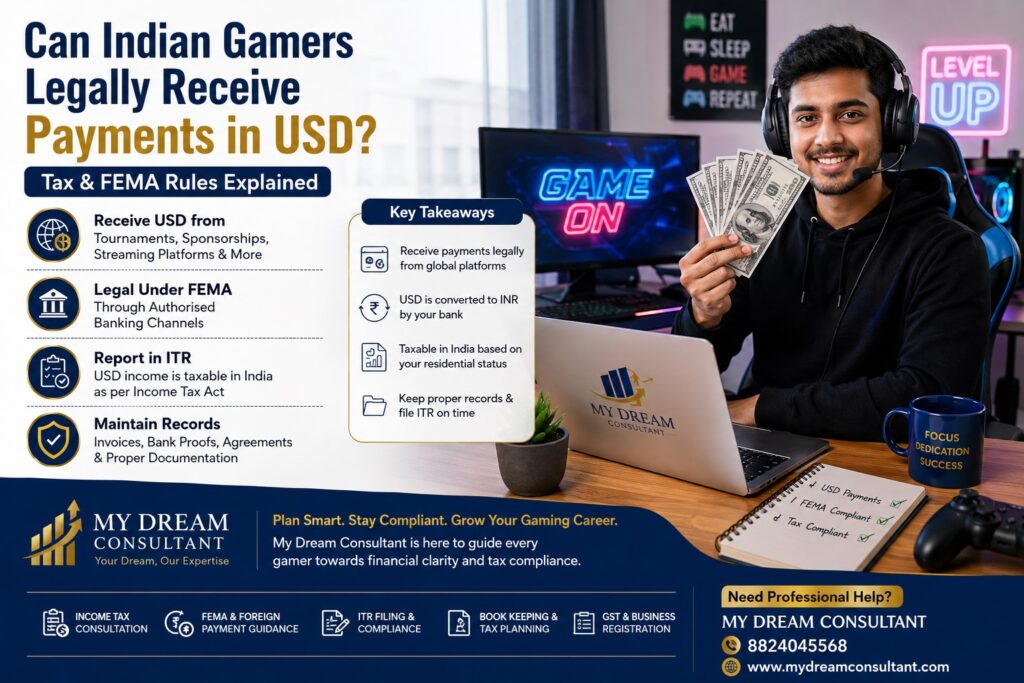
Introduction The gaming industry has transformed from a hobby into a global profession. Today, thousands of Indian gamers earn income from international gaming tournaments, streaming platforms, sponsorships, coaching, affiliate marketing, and gaming content creation. One of the most common questions professional gamers ask is: The simple answer is Yes, Indian gamers can legally receive payments in foreign currencies such as USD, EUR, GBP, AUD, and others, provided they comply with applicable Indian laws, including the Foreign Exchange Management Act (FEMA), Income-tax provisions, and any other relevant regulatory requirements. Unfortunately, many gamers believe that receiving money in USD automatically creates legal problems or that they must open a company abroad to receive foreign payments. Both assumptions are generally incorrect. At My Dream Consultant, we regularly assist gamers, streamers, YouTubers, freelancers, and digital creators in understanding the legal and tax aspects of foreign income. Whether you earn from international gaming tournaments or foreign sponsorships, My Dream Consultant can help you understand the applicable compliance requirements. Why Are Indian Gamers Receiving USD Payments? Gaming has become a global profession. Companies from the United States, Europe, the United Kingdom, Canada, Japan, South Korea, and other countries regularly work with Indian gamers. Common sources of USD income include: International gaming tournaments YouTube Gaming revenue Twitch streaming Kick streaming Sponsorship deals Affiliate marketing Merchandise sales Coaching sessions Brand collaborations Gaming app testing Game reviews Content creation Many of these companies make payments in USD because they operate internationally. My Dream Consultant advises gamers to maintain proper documentation for every foreign payment they receive. Start Your Company In Just A Click —-! Click Here !—- Is It Legal to Receive USD Payments in India? Yes. Receiving foreign currency is generally legal if the payment is for a lawful purpose and is received through authorised banking channels or other permitted payment mechanisms. Gamers should ensure that: The source of income is legitimate. The payment is properly documented. Income is reported correctly in the Income Tax Return where required. FEMA and RBI requirements applicable to the transaction are followed. My Dream Consultant recommends using recognised banking channels and maintaining complete payment records. Understanding FEMA FEMA stands for the Foreign Exchange Management Act, 1999. It regulates foreign exchange transactions in India. FEMA does not prohibit Indian gamers from earning money from foreign clients or gaming companies. Instead, it provides the legal framework for foreign exchange transactions. If you are receiving genuine gaming income, FEMA generally permits such receipts, subject to compliance with applicable rules. This is why My Dream Consultant always encourages gamers to understand both tax and FEMA aspects before expanding internationally. Real-Life Example 1 Rahul is a professional BGMI player from Jaipur. He wins an international tournament organised by a Singapore-based company. Prize Money: USD 3,000 The organiser transfers the amount directly to Rahul’s Indian bank account through authorised banking channels. This is generally a legitimate cross-border payment. Rahul should preserve: Tournament invitation Winner confirmation Payment advice Bank credit Email communication At the time of filing his Income Tax Return, Rahul should consider the applicable reporting requirements. My Dream Consultant helps gamers organise such documents well before the ITR filing season. Can You Receive USD Directly in Your Indian Bank Account? Yes. Many banks in India receive inward foreign remittances through authorised banking channels. The amount is generally converted into Indian Rupees by the receiving bank based on the applicable exchange rate and credited to your account. Always review the bank’s advice or credit confirmation and preserve it for your records. My Dream Consultant recommends keeping a dedicated folder containing all foreign inward remittance records. Start Your Company In Just A Click —-! Click Here !—- Popular Sources of Foreign Gaming Income Indian gamers may receive payments from: International tournament organisers Overseas sponsors Foreign gaming companies International coaching clients Global affiliate programmes Overseas digital marketplaces International eSports organisations Every source should be properly recorded. Professionals at My Dream Consultant often advise creators to maintain separate records for each income source to simplify accounting and return filing. Income Tax on USD Payments Receiving income in USD does not make it tax-free. The taxability depends on several factors, including your residential status under the Income-tax Act and the nature of the income. If the income is taxable in India, it should generally be reported in the appropriate manner while filing your Income Tax Return. The fact that payment was received in a foreign currency does not, by itself, change the reporting obligation. My Dream Consultant assists clients in understanding how foreign income should be evaluated and reported. Real-Life Example 2 Priya is a gaming content creator. She earns: USD 500 from an overseas sponsor. USD 700 from coaching international gamers. USD 900 from affiliate marketing. Although the payments are in USD, she should maintain proper records of the receipts, exchange rate used for accounting purposes, and supporting documents. With guidance from My Dream Consultant, she prepares organised financial records before filing her return. Start Your Company In Just A Click —-! Click Here !—- Should Gamers Maintain Books of Accounts? If you regularly earn gaming income, maintaining proper books of accounts is a good business practice and may also be required in certain situations under the Income-tax Act. Maintain records such as: Income register Bank statements Invoices Sponsorship agreements Affiliate statements Tournament results Expense bills Foreign payment confirmations My Dream Consultant encourages gamers to maintain digital records throughout the year instead of waiting until the tax filing deadline. Can Gamers Receive Payments Through PayPal or Wise? Many international clients and platforms use payment service providers. Before using any payment method, ensure that it complies with applicable laws and the provider’s terms and conditions. Always preserve: Transaction IDs Payment confirmations Settlement reports Bank credits My Dream Consultant can help you organise these records for accounting and tax purposes. Business Expenses Gamers Should Track If you earn gaming income as a business or profession, maintaining records of eligible business expenses is important. Examples may
Why You Received an Income Tax Notice & What to Do Next
Introduction Receiving an Income Tax notice can make anyone anxious. The moment people see an email or message from the Income Tax Department, questions immediately arise: Did I make a mistake? Am I being penalized? Will I have to pay extra tax? What should I do now? The first thing to understand is this — receiving an Income Tax notice does not always mean you have done something wrong. In many cases, notices are issued for simple reasons like missing information, mismatch in income reporting, incorrect ITR filing, delayed filing, or verification issues. With the Income Tax Department using advanced AI-based tracking systems, AIS, TIS, Form 26AS, and digital compliance tools, income mismatches are detected faster than ever. This is why many taxpayers now seek guidance from experienced Income Tax Consultants, the Best CA in Jaipur, or experts offering ITR Filing in Jaipur to avoid notices and stay compliant. In this blog, we will understand why you may receive an Income Tax notice and what steps you should take next. What is an Income Tax Notice? An Income Tax notice is an official communication sent by the Income Tax Department to a taxpayer. The notice may ask you to: Provide clarification Correct information Submit missing documents Pay pending tax Respond to mismatched transactions Not every notice is a penalty notice. Some are simply informational or compliance-related. Start Your Company In Just A Click —-! Click Here !—- Common Reasons for Receiving an Income Tax Notice Let’s understand the most common reasons. Mismatch Between ITR and AIS / Form 26AS One of the most common reasons is mismatch in reported income. Your filed ITR may not match data available with the department from: AIS TIS Form 26AS Banks Employers Brokers If income shown in these records differs from your ITR, a notice may be generated. Real-Life Example 1 Rahul filed his ITR using only Form 16. However, he forgot to include FD interest income. Since the bank had already reported the interest to the Income Tax Department, AIS showed extra income. Result: Rahul received a notice asking for clarification. High-Value Transactions The Income Tax Department tracks major financial transactions such as: Large cash deposits Property purchases Credit card spending Foreign travel expenses Stock market transactions Mutual fund investments If your transactions appear high compared to declared income, the department may seek clarification. Real-Life Example 2 Priya reported annual income of ₹8 lakh. During the same year, she purchased property worth ₹70 lakh. The transaction triggered scrutiny because declared income did not justify the purchase. She received a notice requesting source details. Not Filing ITR Even if tax is deducted through TDS, non-filing can attract notices. This especially happens when: TDS exists in Form 26AS Large transactions are recorded Income exceeds filing threshold The department may ask why the return was not filed. Incorrect ITR Form Choosing the wrong ITR form is a common mistake. For example: Business income filed in salary form Capital gains ignored Rental income incorrectly reported Wrong filing can trigger compliance issues. Claiming Excess Deductions Claiming deductions without valid proof can attract scrutiny. Examples include: Fake investment declarations Incorrect HRA claims Inflated deductions Unsupported exemptions Always keep documentation ready. Mismatch in TDS Credit Many taxpayers claim TDS credit incorrectly. Common issues include: Wrong TAN Missing TDS entries Duplicate claims Incorrect amount claimed This often leads to tax notices. Real-Life Example 3 Amit claimed full TDS credit based on salary records. However, employer reporting had errors. The mismatch resulted in an automated notice. After correction, the issue was resolved. Late ITR Filing Late filing can trigger: Penalty Interest Compliance notices Timely filing reduces risk. This is why many people search for ITR Filing Near Me or professional tax assistance before deadlines. Income from Shares, Crypto, or Mutual Funds Not Reported Many taxpayers forget to disclose: Capital gains Dividend income Trading income Crypto profits Since brokers report many transactions digitally, omissions can trigger notices. Types of Income Tax Notices Different notices serve different purposes. Common notice categories include: Defective Return Notice Errors found in filed return. Scrutiny Notice Detailed examination of return. Demand Notice Tax payable after assessment. Refund Adjustment Notice Refund adjusted against dues. Non-Filing Notice ITR not filed despite taxable income. What Should You Do After Receiving a Notice? Do not panic. Follow these steps. Step 1: Read the Notice Carefully Check: Notice section Assessment year Response deadline Reason for notice Understanding the exact issue is critical. Step 2: Verify Whether Notice is Genuine Always verify notices through the official Income Tax portal. Avoid fraud emails or fake messages. Step 3: Gather Required Documents Collect relevant documents such as: PAN Aadhaar Form 16 Bank statements AIS Form 26AS Investment proofs Property records Documentation helps build your response. Step 4: Compare Data with Your ITR Review your filed return. Check for: Missing income Wrong deduction TDS mismatch Calculation errors Many issues can be identified quickly. Step 5: Consult a Professional Tax Expert This is often the safest step. Experienced Income Tax Consultants can help: Understand the notice Draft replies Prepare documentation Respond accurately Avoid penalties That is why many taxpayers search for: Top CA in Jaipur Best CA in Jaipur ITR Filing in Jaipur Income Tax Consultants before replying to notices. What Happens If You Ignore a Tax Notice? Ignoring a notice can lead to serious consequences. Possible outcomes include: Penalties Interest Refund blockage Additional tax demand Assessment proceedings Legal complications Responding on time is very important. Real-Life Example 4 Rohit ignored a notice thinking it was unimportant. Months later, penalty and interest were added. A small mismatch became a bigger financial issue. Professional help could have saved him time and money. How to Avoid Income Tax Notices You can reduce notice risk by following simple habits. File ITR on Time Avoid last-minute filing. Report All Income Include every income source. Check AIS & TIS Cross-verify before filing. Use Correct ITR Form Wrong form causes issues. Maintain Documents Keep proofs safely. Seek Expert Guidance Professional filing reduces mistakes.
Income Tax on Share Market & Mutual Fund Income Explained
Introduction Investing in the share market and mutual funds has become increasingly popular in India. Today, salaried employees, business owners, professionals, freelancers, and even students are investing to build long-term wealth. However, while many people focus on earning profits from investments, they often ignore one important aspect—taxation. A common question investors ask is: Is profit from shares taxable? How are mutual fund gains taxed? What is LTCG and STCG? Is dividend income taxable? How should these incomes be reported in ITR? Understanding taxation on investments is extremely important because incorrect reporting can lead to notices, penalties, or excess tax payments. This is why many investors seek help from Income Tax Consultants, the Best CA in Jaipur, or professionals offering ITR Filing in Jaipur to ensure proper tax compliance. In this guide, we will explain taxation on share market and mutual fund income in simple language with practical examples. Start Your Company In Just A Click —-! Click Here !—- Types of Income from Shares & Mutual Funds Income from investments generally comes from two sources: 1. Capital Gains Profit earned when you sell shares or mutual fund units at a higher price than purchase cost. 2. Dividend Income Income received when companies or mutual funds distribute profits to investors. Both are taxed differently. What is Capital Gain? Capital gain means profit earned from selling an asset. Formula Capital Gain = Selling Price – Purchase Price – Eligible Expenses Capital gains are divided into: Short-Term Capital Gain (STCG) Long-Term Capital Gain (LTCG) Tax treatment depends on the holding period. Short-Term Capital Gain (STCG) on Shares If listed equity shares or equity mutual funds are sold within the short-term holding period, profit is treated as Short-Term Capital Gain (STCG). STCG is generally taxed at a special rate under applicable tax laws. Real-Life Example 1 Rahul bought shares worth ₹2,00,000. After 8 months, he sold them for ₹2,60,000. Profit earned = ₹60,000 Since he sold within a short period, this gain is treated as STCG and taxed accordingly. Long-Term Capital Gain (LTCG) on Shares If shares or equity mutual funds are held beyond the prescribed long-term holding period, profits are classified as Long-Term Capital Gain (LTCG). LTCG often receives more favorable tax treatment compared to STCG. Real-Life Example 2 Priya invested ₹5,00,000 in equity mutual funds. After 3 years, the investment grew to ₹8,50,000. Profit = ₹3,50,000 Since the holding period qualifies as long-term, the gains are taxed under LTCG rules. Tax on Mutual Funds Mutual fund taxation depends on the type of fund. Different categories include: Equity Mutual Funds Debt Mutual Funds Hybrid Funds International Funds Tax treatment differs based on fund structure and holding period. This is where many investors get confused and seek guidance from experienced Income Tax Consultants. Tax on Dividend Income Earlier, dividend income enjoyed different tax treatment. Now, dividend income is generally taxable in the hands of the investor. Dividend income received from: Shares Mutual Funds Corporate Investments must be reported while filing Income Tax Return. Real-Life Example 3 Amit owns shares in multiple listed companies. During the year, he received ₹45,000 as dividends. Initially, he ignored this income while filing ITR. Later, AIS reflected dividend details, creating a mismatch. After consulting a tax professional, he corrected his return. Intraday Trading Income Intraday trading has separate tax treatment. Buying and selling shares on the same day is generally treated differently from normal investment activity. Income from intraday trading may be treated as speculative business income depending on transaction nature. Proper reporting becomes crucial. Futures & Options (F&O) Taxation Income from derivatives like: Futures Options is generally considered business income rather than capital gains. Tax calculation for F&O can become complex due to: Turnover calculation Expense claims Audit applicability Loss adjustment Professional assistance is highly recommended. Can You Set Off Losses? Yes, investment losses may help reduce taxable income subject to tax rules. Examples include: Share market losses Mutual fund losses Capital losses Proper tax planning can help optimize gains and losses. Real-Life Example 4 Rohit earned: Profit from shares: ₹1,50,000 Loss from mutual funds: ₹40,000 With proper tax planning, eligible losses helped reduce taxable gains. Without guidance, he could have paid unnecessary tax. Common Mistakes Investors Make Many investors make errors such as: Not Reporting Capital Gains Even small profits should be reviewed carefully. Ignoring Dividend Income Dividend income is often forgotten. Wrong Gain Classification Confusing STCG and LTCG is common. Ignoring AIS/TIS Investment transactions often reflect in AIS. Incorrect ITR Form Wrong ITR selection creates filing issues. How Share Market Income Affects ITR Filing Investment income impacts ITR filing significantly. You may need to disclose: Capital gains Dividend income Trading income Losses carried forward Business income (for traders) Incorrect disclosure can lead to: Notices Refund delays Tax demand Penalties This is why many taxpayers search for: Top CA in Jaipur Best CA in Jaipur ITR Filing in Jaipur Income Tax Consultants ITR Filing Near Me before filing returns. Why Professional Guidance Matters Taxation on investments can become complicated when you have: Multiple demat accounts SIP investments F&O trading International investments Dividend income Frequent trading A professional tax consultant helps with: Accurate tax calculation Gain classification Loss adjustment Compliance planning Correct ITR filing Documents Required for Tax Filing Keep these ready: Broker statements Capital gain statements Mutual fund reports Dividend statements Bank statements AIS Form 26AS These documents help ensure accurate filing. Tax Saving Tips for Investors Hold Investments Longer Long-term investing may provide better tax efficiency. Plan Profit Booking Timing matters in taxation. Use Loss Harvesting Strategic loss booking can optimize taxes. Maintain Proper Records Documentation avoids future disputes. Consult Experts Professional planning saves tax legally. Conclusion Investing in shares and mutual funds can help create wealth, but understanding taxation is equally important. Ignoring tax implications may lead to penalties, notices, or unnecessary tax payments. Whether your income comes from capital gains, dividends, trading, or mutual fund redemptions, proper reporting in ITR is essential. If you invest actively in the stock market or mutual funds,
How to Claim Income Tax Refund Faster
Introduction One of the most satisfying moments for taxpayers is receiving an Income Tax Refund. Whether you are a salaried employee, business owner, freelancer, professional, or investor, getting a refund means that you have paid more tax than your actual tax liability during the financial year. However, many taxpayers often face delays in receiving their refunds due to mistakes in Income Tax Return (ITR) filing, incorrect bank details, mismatched information, or incomplete verification. The good news is that by following a few simple steps, you can significantly increase the chances of receiving your refund quickly and without complications. In this guide, we will explain how Income Tax Refunds work, common reasons for delays, and practical tips to help you get your refund faster. What is an Income Tax Refund? An Income Tax Refund is the amount returned by the Income Tax Department when the tax paid by a taxpayer exceeds their actual tax liability. This excess tax may arise due to: Excess TDS deduction by employer TDS deducted by banks on FD interest Advance tax paid in excess Self-assessment tax paid more than required Incorrect tax estimation during the year Once the Income Tax Department processes your return and confirms the excess payment, the refund is credited directly to your bank account. Start Your Company In Just A Click —-! Click Here !—- Why Do Taxpayers Receive Refunds? Some common situations include: Excess TDS on Salary Employers may deduct more tax than necessary. TDS on Fixed Deposits Banks deduct TDS on FD interest even when actual tax liability is lower. Multiple Sources of Income Tax calculations may not be accurately adjusted during the year. Incorrect Tax Estimation Taxpayers may pay extra advance tax to avoid penalties. Real-Life Example 1 Ramesh works in a private company and earns ₹9 lakh annually. His employer deducted TDS throughout the year. However, after claiming deductions under eligible provisions, his actual tax liability became lower than the TDS already deducted. After filing his ITR correctly, he received a refund directly into his bank account. Step 1: File Your ITR on Time One of the most important factors in receiving a faster refund is filing your Income Tax Return before the due date. Benefits of timely filing: Faster processing Early refund issuance Lower risk of notices Better compliance record Many taxpayers searching for ITR filing near me or ITR filing in Jaipur choose professional assistance to avoid delays. Step 2: Choose the Correct ITR Form Using the wrong ITR form can result in: Defective return notices Processing delays Refund hold-ups Examples: ITR-1 for eligible salaried individuals ITR-2 for capital gains and multiple income sources ITR-3 for business income ITR-4 for presumptive taxation cases A top CA in Jaipur can help identify the correct form. Step 3: Verify AIS and Form 26AS Before filing your return, review: AIS (Annual Information Statement) Contains: Salary details Interest income Share transactions Mutual fund transactions High-value transactions Form 26AS Contains: TDS credits Tax payments Refund history Mismatches between your return and these records often lead to delays. Real-Life Example 2 Priya filed her return without checking AIS. Later, the Income Tax Department identified unreported FD interest income. The return processing was delayed until the discrepancy was resolved. Checking AIS beforehand could have prevented the issue. Step 4: Report All Income Correctly Many taxpayers unintentionally omit: Savings account interest FD interest Dividend income Capital gains Freelance income Incomplete reporting may delay processing and trigger scrutiny. Always disclose all income sources accurately. Step 5: Pre-Validate Your Bank Account Income tax refunds are directly credited to your bank account. Ensure that: Account number is correct IFSC code is correct Bank account is pre-validated PAN is linked to the bank account Incorrect bank details are among the most common reasons for refund failures. Step 6: Complete E-Verification Immediately After filing your return, it must be verified. Methods include: Aadhaar OTP Net banking Bank account verification Demat account verification Many taxpayers forget this step, causing unnecessary delays. A return is processed only after successful verification. Real-Life Example 3 Neha filed her ITR on time but forgot to e-verify it. The return remained unprocessed for several weeks. After completing verification, the refund process started successfully. Step 7: Claim All Eligible Deductions Correctly Proper deduction claims reduce taxable income and may increase refund amounts. Common deductions include: Health Insurance Premiums Eligible medical insurance payments. Home Loan Benefits Interest and principal repayment benefits. Retirement Investments Eligible long-term savings and pension contributions. Education Loan Interest Interest paid on eligible education loans. Proper documentation should always be maintained. Step 8: Avoid Frequent Revisions Frequent revisions may: Delay processing Trigger additional review Slow refund issuance Double-check all information before submitting the return. Step 9: Respond Quickly to Notices If the Income Tax Department requests clarification: Respond promptly Provide accurate documents Follow instructions carefully Delays in responding may postpone refunds. Common Reasons for Refund Delays Incorrect Bank Details Wrong account information prevents refund credit. Unverified Return ITR must be verified after filing. Income Mismatch Differences between return and AIS/Form 26AS. Pending Tax Demands Outstanding demands may be adjusted against refunds. Wrong ITR Form Incorrect filing may lead to defective return notices. Why Professional Assistance Helps Many taxpayers assume refund claims are simple. However, issues often arise due to: Complex income sources Capital gains reporting Business income Foreign income Deduction claims Professional income tax consultants can help ensure: Accurate filing Faster processing Proper refund claims Compliance with tax laws This is why many people search for: Best CA in Jaipur Top CA in Jaipur Income Tax Consultants ITR Filing Near Me before filing their returns. Tips for Faster Income Tax Refunds File Early Avoid waiting until the deadline. Verify Bank Details Ensure account information is correct. Match AIS & Form 26AS Review all records before filing. Report Complete Income Do not omit any earnings. E-Verify Immediately Verification is essential for processing. Seek Professional Advice Experts help minimize filing errors. Conclusion Receiving an Income Tax Refund does not have to be a lengthy process.
How Business Owners Can Reduce Tax Legally in India
Running a business is not just about increasing sales and profits. Smart business owners also focus on reducing their tax liability legally. Many entrepreneurs end up paying more tax than necessary simply because they are unaware of the deductions, exemptions, and tax planning opportunities available under Indian tax laws. The good news is that tax reduction does not mean tax evasion. With proper planning and professional guidance, business owners can legally minimize their tax burden while remaining fully compliant with the Income Tax Act. In this comprehensive guide, we will discuss practical strategies that business owners can use to reduce taxes legally in India. Introduction Every business owner wants to maximize profits. However, a significant portion of profits often goes toward taxes. Many small and medium-sized businesses miss valuable tax-saving opportunities because they do not maintain proper records or seek professional advice. Whether you are a trader, manufacturer, consultant, freelancer, startup founder, or service provider, understanding legal tax-saving methods can help improve your business’s financial health. This is why many entrepreneurs regularly consult income tax consultants, the best CA in Jaipur, and professionals specializing in ITR filing in Jaipur to ensure effective tax planning. Start Your Company In Just A Click —-! Click Here !—- Why Tax Planning Is Important for Business Owners Tax planning helps businesses: Reduce overall tax liability Improve cash flow Increase profitability Avoid penalties and notices Ensure smooth compliance Support future business growth Tax planning should be done throughout the year and not just at the time of filing Income Tax Returns. Real-Life Example Raj owns a trading business in Jaipur with an annual profit of ₹25 lakh. Initially, he maintained poor records and did not claim legitimate business expenses. As a result, his taxable income remained high. After consulting a top CA in Jaipur, he properly documented expenses such as office rent, internet bills, staff salaries, travel expenses, and depreciation on assets. This significantly reduced his taxable income and helped him save a substantial amount of tax legally. Maintain Proper Books of Accounts One of the most important steps in tax planning is maintaining accurate financial records. Business owners should maintain: Sales records Purchase invoices Expense bills Bank statements GST records Payroll records Proper bookkeeping ensures that every eligible deduction can be claimed during tax filing. Claim All Legitimate Business Expenses Many business owners fail to claim expenses they are legally entitled to deduct. Common deductible expenses include: Office Rent Rent paid for business premises can be claimed as an expense. Employee Salaries Staff salaries and wages are fully deductible. Electricity and Utility Bills Business-related utility expenses reduce taxable profits. Internet and Mobile Expenses Communication expenses used for business purposes are deductible. Professional Fees Payments made to accountants, lawyers, consultants, and auditors can be claimed. Marketing and Advertising Expenses Expenses on social media promotions, Google Ads, and branding activities are deductible. Real-Life Example A digital marketing agency spent ₹4 lakh annually on advertising and software subscriptions. Since these expenses were directly related to business operations, they reduced the firm’s taxable income significantly. Claim Depreciation on Business Assets Businesses can claim depreciation on assets such as: Computers Laptops Office furniture Machinery Vehicles Equipment Depreciation reduces taxable income every year while reflecting the gradual wear and tear of assets. Use Presumptive Taxation Schemes Small businesses and professionals may benefit from presumptive taxation schemes under Sections 44AD and 44ADA. Benefits include: Simplified compliance Reduced paperwork Easier tax calculation Lower accounting burden This option is particularly useful for small business owners, consultants, and freelancers. Invest in Tax-Saving Instruments Business owners can also reduce personal tax liability through eligible investments. Popular options include: Public Provident Fund (PPF) ELSS Mutual Funds Life Insurance Premiums Tax Saver Fixed Deposits National Pension System (NPS) These investments may provide deductions under applicable provisions of the Income Tax Act. Choose the Right Business Structure The legal structure of a business can significantly impact taxation. Common business structures include: Sole Proprietorship Partnership Firm LLP Private Limited Company Each structure has different tax implications. Professional guidance from income tax consultants can help determine the most tax-efficient structure. Real-Life Example A growing consulting business converted from a proprietorship to an LLP. The restructuring improved compliance, enhanced credibility, and offered better tax planning opportunities. Separate Personal and Business Expenses Many small business owners mix personal and business transactions. This creates problems during: Audits Tax assessments Loan applications ITR filing Maintaining separate business bank accounts improves financial transparency and tax compliance. Utilize GST Input Tax Credit Businesses registered under GST can claim Input Tax Credit (ITC) on eligible purchases. This helps reduce overall tax costs and improves working capital management. Proper GST compliance is essential to maximize available credits. Plan Capital Expenditure Carefully Purchasing business assets before the financial year-end may provide depreciation benefits. Strategic planning of business investments can optimize tax savings while supporting growth. File Income Tax Returns on Time Late filing can result in: Penalties Interest charges Delayed refunds Compliance issues Timely filing helps maintain a clean tax record and avoid unnecessary costs. This is why many business owners search for: ITR filing near me ITR filing in Jaipur Best CA in Jaipur Top CA in Jaipur to ensure accurate and timely filing. Common Tax Mistakes Business Owners Should Avoid Some common mistakes include: Not maintaining invoices Mixing personal and business expenses Ignoring GST compliance Claiming unsupported deductions Delaying tax payments Not consulting professionals Avoiding these mistakes can save both money and stress. Why Professional Tax Guidance Matters Tax laws change frequently, and business owners may struggle to keep up with every update. Professional tax experts help with: Tax planning Return filing GST compliance Audit support Notice handling Financial planning This is why many entrepreneurs prefer working with experienced income tax consultants and the best CA in Jaipur. Conclusion Reducing taxes legally is not about finding loopholes. It is about understanding the law and making informed financial decisions. Business owners who maintain proper records, claim eligible deductions, plan investments wisely, and seek professional guidance can significantly
New Income Tax Rules Every Taxpayer Must Know in 2026
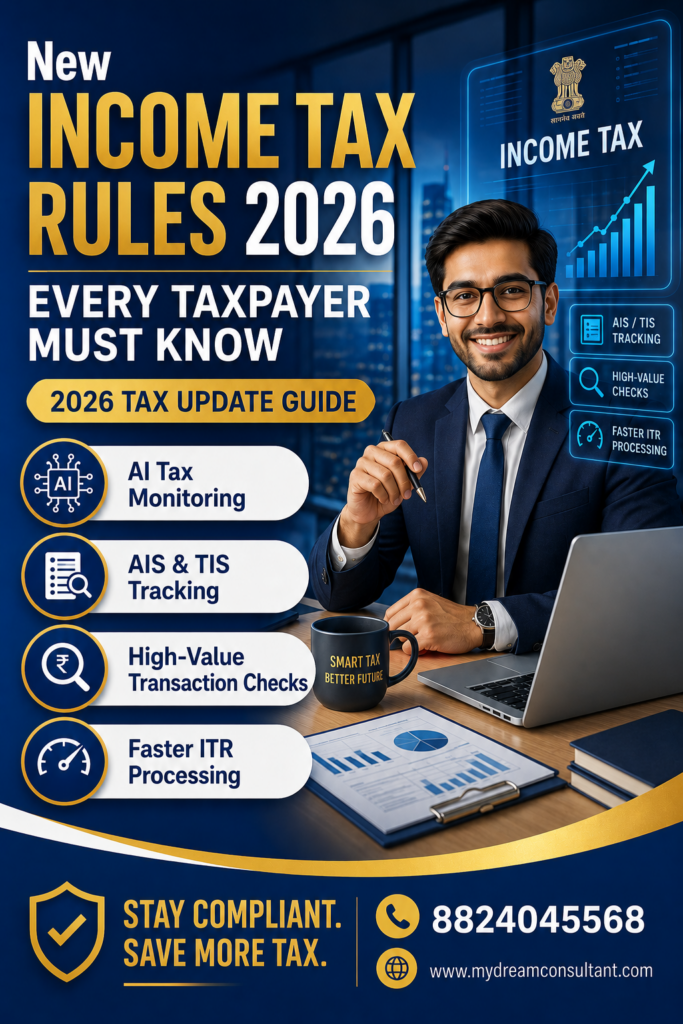
The Income Tax Department has introduced several important changes in 2026 that every taxpayer should understand. Whether you are a salaried employee, business owner, freelancer, investor, or NRI, these updates can directly impact your tax filing, compliance, refunds, and financial planning. Many people ignore tax updates until they receive a notice or penalty. But understanding the latest income tax rules can help you save money legally and avoid future complications. In this blog, we will explain the latest income tax changes in simple language with real-life examples so that every taxpayer can easily understand them. Why These New Tax Rules Matter in 2026 The government is focusing heavily on: Digital tax monitoring AI-based scrutiny systems High-value transaction tracking Faster tax compliance Simplified filing process Today, the Income Tax Department can track: Bank transactions Property purchases Share market investments Credit card spending Foreign remittances Cryptocurrency transactions This means taxpayers need to be more careful and transparent while filing returns. Start Your Company In Just A Click —-! Click Here !—- AI-Based Income Tax Monitoring System One of the biggest changes in 2026 is the increased use of Artificial Intelligence (AI) by the Income Tax Department. The department now uses advanced systems to detect: Unreported income Fake deductions High cash transactions Mismatch in ITR and AIS/TIS Suspicious banking activities Real-Life Example Suppose a person files an ITR showing annual income of ₹6 lakh, but their bank account reflects: International trips High credit card spending Property investment worth ₹40 lakh The AI system may automatically flag the return for scrutiny. This is why consulting experienced income tax consultants or the best CA in Jaipur has become more important than ever. AIS & TIS Are Becoming More Powerful AIS (Annual Information Statement) and TIS (Taxpayer Information Summary) now contain detailed financial information. These reports may include: Bank interest Share trading Mutual fund investments Property transactions Foreign remittances TDS details Before filing ITR, taxpayers should carefully verify these reports. Real-Life Example Many taxpayers forget to report FD interest because TDS was already deducted by the bank. However, AIS already reflects this income. If it is not reported in ITR, a notice may come later. This is one of the most common mistakes seen during ITR filing in Jaipur and other cities. Stricter Rules for High-Value Transactions The Income Tax Department is now closely monitoring high-value transactions such as: Cash deposits Property purchases Luxury spending Large stock market investments Foreign travel expenses Real-Life Example If someone deposits ₹15 lakh cash in a savings account but files very low income in ITR, the department may ask for the source of funds. Proper documentation is now extremely important. Faster Processing of ITR & Refunds The good news is that ITR processing has become much faster in 2026. If: Your return is correctly filed No mismatch exists Verification is completed on time Then refunds may come quickly. However, even small errors can delay refunds significantly. This is why many people now search for: “ITR filing near me” “Top CA in Jaipur” “Best income tax consultants” to avoid filing mistakes. New Focus on Freelancers & Digital Income Freelancers, influencers, YouTubers, digital marketers, and online sellers are now under greater tax monitoring. Income from: YouTube Instagram promotions Freelancing websites Affiliate marketing Cryptocurrency Online coaching must be properly disclosed. Real-Life Example A freelancer earning through foreign clients receives payments in PayPal and bank accounts. Even if no TDS is deducted, the income is still taxable in India. Many freelancers wrongly assume online income is not traceable. But now digital tracking systems are highly advanced. Increased Scrutiny of Property Transactions Property buyers and sellers should be extra careful in 2026. The department now verifies: Property value Stamp duty valuation TDS compliance Capital gains calculation Real-Life Example If someone sells a property but does not report capital gains correctly, they may receive a tax notice later. This is why property taxation should always be planned with experienced professionals and the top CA in Jaipur. Cryptocurrency & Virtual Asset Tax Rules Continue Cryptocurrency transactions remain under strict monitoring. Key points: 30% tax on profits 1% TDS on transactions Loss adjustment restrictions Even small crypto transactions may now reflect in tax records. Importance of Proper Tax Planning Tax planning is no longer only for big businesses. Today every taxpayer should plan: Investments Deductions Capital gains Business expenses Salary structure Rental income Proper planning helps reduce tax legally while remaining compliant. Common Mistakes Taxpayers Should Avoid in 2026 Here are some major mistakes people still make: Not reporting all income Ignoring AIS/TIS mismatch Claiming fake deductions Filing wrong ITR form Delaying ITR filing Ignoring notices from Income Tax Department Incorrect capital gains reporting These mistakes can result in: Penalties Interest charges Notices Scrutiny cases Why Professional Guidance Is Important Income tax rules are becoming more technical every year. A professional consultant can help you: File accurate returns Reduce tax legally Avoid notices Handle scrutiny Plan investments properly This is why many taxpayers prefer working with: The best CA in Jaipur Experienced income tax consultants Experts for ITR filing in Jaipur Conclusion The new income tax rules in 2026 clearly show that the government is moving toward a more transparent and technology-driven tax system. Whether you are salaried, self-employed, freelancer, investor, or business owner, proper tax compliance is now more important than ever. The best approach is: Maintain proper records File ITR on time Report all income correctly Take professional guidance when needed With proper planning and expert advice, taxpayers can avoid penalties and save taxes legally. Frequently Asked Questions (FAQs) What is the biggest income tax change in 2026? The biggest change is the increased use of AI-based monitoring and tracking systems by the Income Tax Department. Can the Income Tax Department track bank transactions? Yes, high-value and suspicious transactions can be tracked through AIS, TIS, and banking systems. Is AIS important while filing ITR? Yes, AIS is extremely important because it contains detailed financial information linked to your PAN. What happens if income shown in
Common Mistakes NRIs Make While Selling Property in India (2026 Guide)
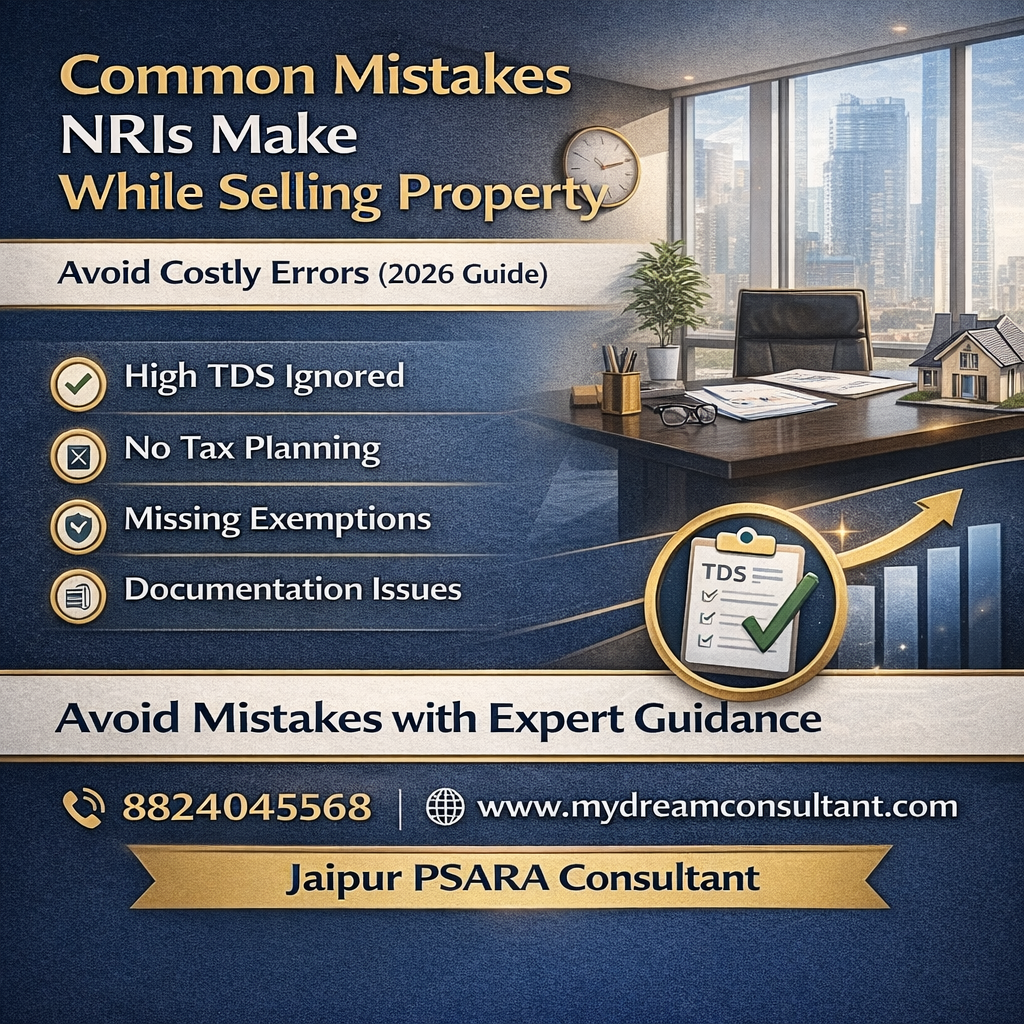
Selling property in India as a Non-Resident Indian (NRI) involves multiple legal, tax, and compliance steps. Many NRIs face challenges due to lack of proper guidance, leading to higher taxes, delays, and complications. This blog highlights the most common mistakes NRIs make and how to avoid them effectively. 🌍 Why NRIs Face Challenges in Property Sale NRIs often deal with: Complex tax rules High TDS deductions FEMA regulations Documentation issues 👉 This is why many prefer guidance from the best NRI tax consultant in India or the top NRI tax consultant in Jaipur. Start Your Company In Just A Click —-! Click Here !—- 🚫 Common Mistakes NRIs Make While Selling Property Lack of Understanding of Capital Gains Tax Many NRIs are unaware of: Short-Term Capital Gains (STCG) Long-Term Capital Gains (LTCG) This leads to poor tax planning and higher tax liability. Ignoring High TDS Deduction Buyers deduct 20%+ TDS on property sale Often higher than actual tax liability 👉 Applying for a Lower TDS Certificate can help reduce this burden. Not Claiming Available Tax Exemptions NRIs often miss benefits like: Section 54 (reinvestment in property) Section 54EC (capital gain bonds) This results in unnecessary tax payments. Poor or Incomplete Documentation Common issues include: Missing title documents Incomplete agreements Unclear ownership records Improper Use of Power of Attorney NRIs living abroad may: Delay appointing a PoA Use improperly attested documents This can delay the transaction significantly. Ignoring DTAA Benefits NRIs may end up paying tax in both: India Country of residence DTAA helps avoid double taxation if used properly. Delay in Filing Income Tax Return Delayed ITR filing can lead to penalties Refunds may get delayed Improper Repatriation Planning Common issues include: Missing Form 15CA/15CB Not following RBI guidelines Delay in transferring funds abroad Incorrect Property Valuation Selling below market value Wrong calculation of capital gains This may increase tax liability or create compliance issues. Not Taking Professional Advice Handling everything independently can lead to: Tax calculation errors Missed deadlines Financial losses 👉 Consulting the top NRI tax consultant in India ensures proper planning and compliance. 🏢 How to Avoid These Mistakes Plan your property sale in advance Understand tax implications Maintain proper documentation Use legal tax-saving options Seek expert guidance 💼 Why You Need a Professional NRI Tax Consultant A professional consultant helps: Reduce tax liability Manage TDS efficiently Handle compliance and documentation Ensure smooth repatriation 👉 Choosing the best NRI tax consultant in Jaipur or the top NRI tax consultant in India ensures a hassle-free process. 🔍 SEO Keywords Included Common Mistakes NRI Property Sale India NRI Property Sale Problems Best NRI Tax Consultant in India Top NRI Tax Consultant in India Best NRI Tax Consultant in Jaipur Top NRI Tax Consultant in Jaipur NRI Tax Planning India TDS on Property Sale NRI ✨ Final Thoughts Selling property in India as an NRI requires proper planning and awareness. Avoiding common mistakes can save you from unnecessary tax burdens and legal complications. With the right support from the best NRI tax consultant in India, you can ensure a smooth and profitable transaction. 📞 Call to Action Planning to sell your property in India? Connect with the top NRI tax consultant in Jaipur for expert guidance and stress-free execution. 👉 Contact us today! #NRIPropertySale#NRITaxation#NRIIndia#PropertySaleIndia#TaxPlanningIndia#CapitalGains #TDSIndia#NRIConsultant #JaipurConsultant#CAinJaipur#TaxConsultantJaipur #BestNRITaxConsultant#TopNRITaxConsultant
How to Repatriate Money After Property Sale in India (NRI Guide 2026)
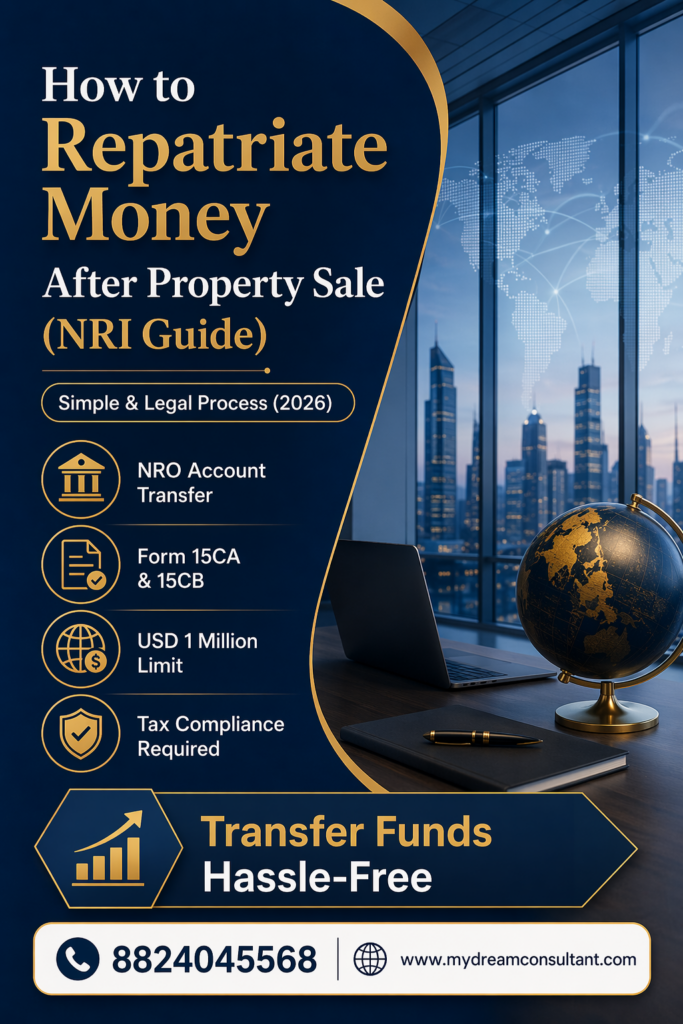
Selling property in India is only half the process for NRIs—the next crucial step is repatriating (transferring) the sale proceeds abroad. Many NRIs face confusion due to RBI rules, tax compliance, and documentation requirements. This complete guide will help you understand the legal process, limits, documents, and tax implications for smooth fund repatriation. 🌍 What is Repatriation? Repatriation means transferring money from India to your country of residence. 👉 For NRIs, this typically involves transferring funds from an NRO account to a foreign bank account after selling property. 💼 Is Repatriation Allowed for NRIs? Yes, NRIs are allowed to repatriate funds under RBI (Reserve Bank of India) guidelines, subject to certain conditions. ✔ Up to USD 1 million per financial year ✔ Applicable to sale proceeds, rent, and other income Start Your Company In Just A Click —-! Click Here !—- 🧾 Step-by-Step Process to Repatriate Money ✅ Step 1: Deposit Sale Proceeds in NRO Account Property sale amount must be credited to your NRO account Ensure proper documentation of transaction ✅ Step 2: Calculate Tax Liability Capital gains tax must be calculated TDS should be verified Excess TDS can be claimed as refund 👉 Proper tax planning with the best NRI tax consultant in India helps avoid unnecessary deductions. ✅ Step 3: Obtain CA Certificate (Form 15CB) Chartered Accountant certifies: Tax paid Source of funds Compliance with tax laws 👉 This is a mandatory step handled by the top NRI tax consultant in Jaipur. ✅ Step 4: File Form 15CA Online Submit Form 15CA on Income Tax portal Declaration for remittance of funds ✅ Step 5: Submit Documents to Bank Provide the following to your bank: Form 15CA & 15CB PAN Card Property sale documents Bank statements TDS certificates ✅ Step 6: Transfer Funds Abroad Bank processes remittance Funds transferred to your foreign account 👉 Smooth execution is ensured with the best NRI tax consultant in Jaipur. 📊 Important Rules for Repatriation Limit: USD 1 million per financial year Applies to: Property sale proceeds Rental income Other earnings in India 💰 Tax Implications on Repatriation Tax must be paid before repatriation Capital gains tax applicable DTAA can help avoid double taxation 👉 Expert guidance from the top NRI tax consultant in India ensures tax-efficient transfers. ⚠️ Common Mistakes NRIs Should Avoid ❌ Not paying tax before remittance ❌ Missing Form 15CA/CB ❌ Incomplete documentation ❌ Ignoring DTAA benefits ❌ Delays in filing returns 👉 Avoid these issues by consulting the best NRI tax consultant in India. 🏢 Why You Need a Professional NRI Tax Consultant Repatriation involves tax laws, FEMA regulations, and banking compliance. A professional helps: ✔ Accurate tax calculation ✔ Documentation handling ✔ Faster bank processing ✔ DTAA benefit planning ✔ Hassle-free fund transfer 👉 Choosing the top NRI tax consultant in Jaipur ensures a smooth and compliant process 🔍 SEO Keywords Included (High Ranking) This blog is optimized for: NRI Repatriation of Funds India How to Transfer Money Abroad from India NRI NRO to Foreign Account Transfer Best NRI Tax Consultant in India Top NRI Tax Consultant in India Best NRI Tax Consultant in Jaipur Top NRI Tax Consultant in Jaipur NRI Property Sale Repatriation Form 15CA 15CB NRI NRI Tax Planning India ✨ Final Thoughts Repatriating money after property sale in India is a structured process that requires proper compliance with RBI and tax regulations. With the right planning and expert guidance, NRIs can transfer funds smoothly without delays or penalties. Partnering with the best NRI tax consultant in India ensures that your funds are transferred legally, efficiently, and with minimum tax burden. 📞 Call to Action Planning to transfer your property sale funds abroad? Connect with the top NRI tax consultant in Jaipur for expert assistance and hassle-free repatriation. 👉 Contact us today for personalized NRI advisory! #NRIRepatriation#NRIIndia#NRITaxation#PropertySaleIndia #RepatriationOfFunds#NRIPropertySale#Form15CA#Form15CB #JaipurConsultant#CAinJaipur#TaxConsultantJaipur #BestNRITaxConsultant#TopNRITaxConsultant